The Business Loan You Signed Personally Can Shrink Your Mortgage Approval
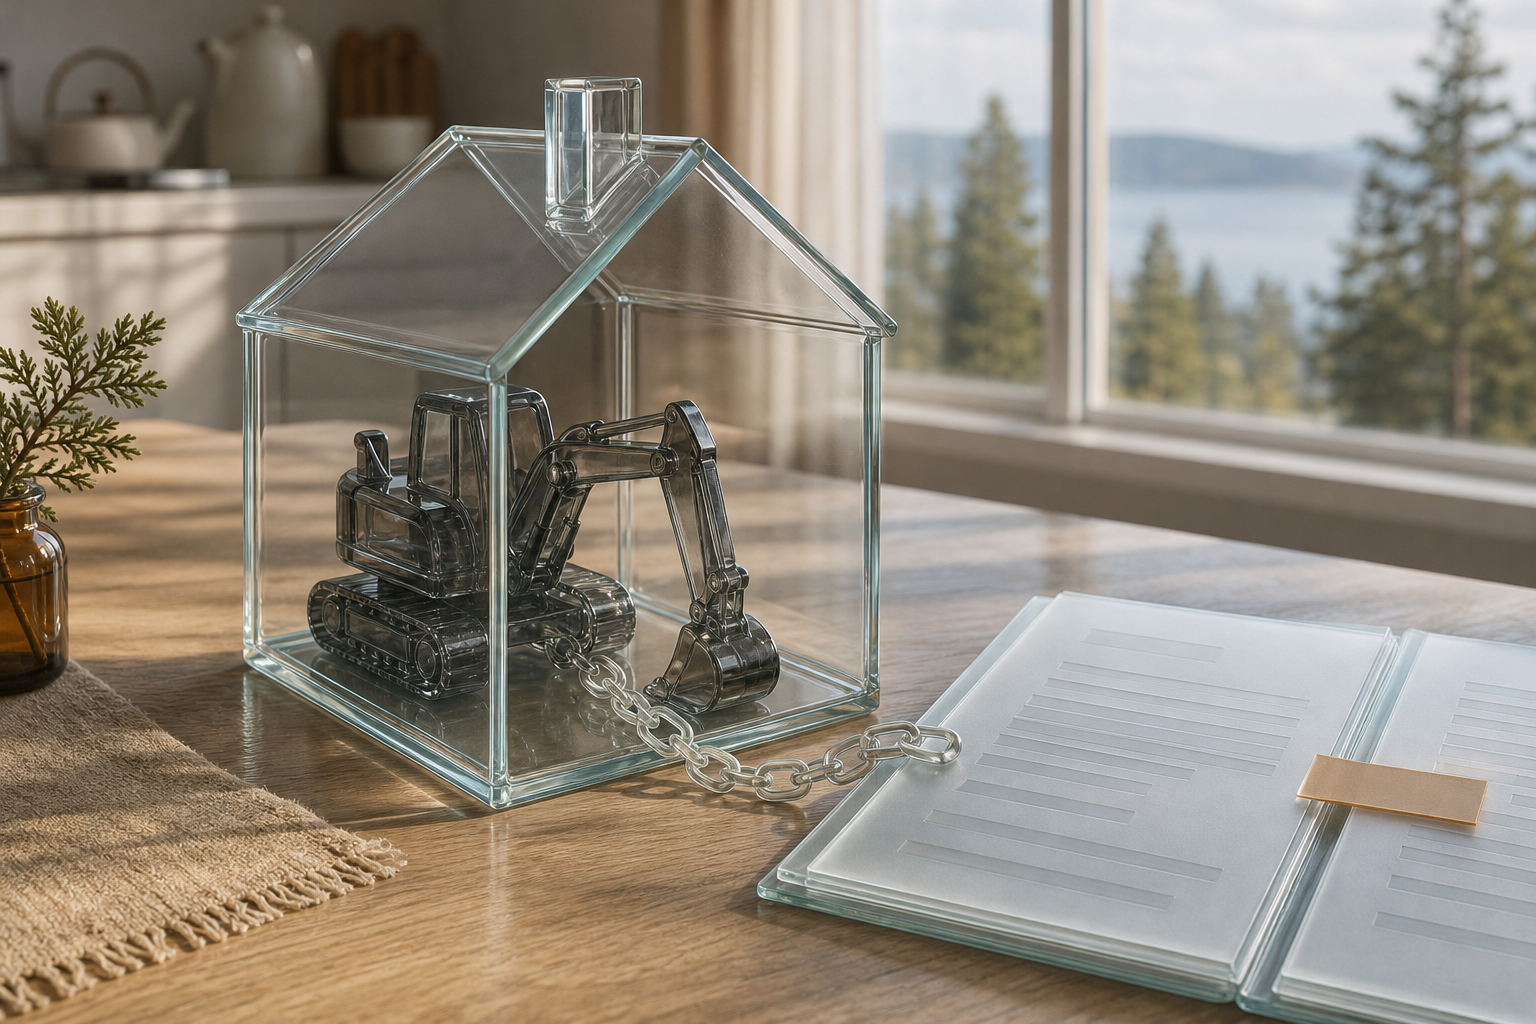
The equipment loan comes out of the company account on a regular schedule, and it has never once bounced. You signed for it personally when the lender asked for a guarantee, and since then it has felt like the business's problem. Then you start planning a home purchase and a mortgage lender asks about it. Knowing what to check before that question comes up keeps your home budget from shrinking after you've already started looking at listings.
If you've sat at the kitchen table working out what your family could afford in Duncan or elsewhere in the Cowichan Valley, you probably left that loan off the page. The business pays it, so it seemed fair to leave it out. Sometimes the lender will agree. But who pays a business loan and who is legally responsible for it are different questions, and a mortgage lender may need answers to both. Learning that late can mean more paperwork, a smaller approval or a closing date that slips.
Check what you personally owe before you set a home budget
A personal guarantee is a promise to repay the company's debt if the company can't. Borrowing directly on your own credit card or line of credit and spending it on the business is different: that debt is yours from day one. Lenders may treat the two differently. A guarantee gives you a reason to look closer before you shop. It doesn't mean your approval will fall.
Identify what you signed. Pull every business financing agreement, lease and supplier credit application from the last few years and look for a guarantee clause with your name on it. People skip this because incorporating felt like it separated them from the company. Incorporating doesn't cancel a guarantee you already signed, and a loan you took out in your own name is personal debt whatever it paid for.
Check both credit reports and your agreements. Order your reports from Equifax Canada and TransUnion Canada. Some business debts show up there and some guarantees don't. A clean report isn't a complete list of your legal obligations, so tell your mortgage professional about any guarantee you found in the paperwork, even if neither bureau shows it.
Find out what the lender will count before you move any money
Once you know what you owe, the next question is how a lender will weigh it. The answer varies by lender and by the type of obligation.
Document who actually pays. Gather the loan terms, the current balance, the monthly payment, and business bank statements showing the company making those payments. Most people expect the lender to take their word for it. Records give the underwriter facts to assess.
Ask how the proposed lender will treat each obligation. Will it count the monthly payment, note the guarantee as a possible liability, or ask for more evidence? Debt payments generally go into your debt-service ratios alongside your housing costs. They aren't simply subtracted from your income. Your mortgage payment is already tested at the higher of your contract rate plus 2 percentage points or 5.25%, so a counted business payment can use up more room than you'd expect. Ask for an affordability review using that lender's actual treatment before you trust any budget figure.
Review changes before you move money. Paying a loan down or asking the business lender for a formal release of your guarantee might improve your numbers. It might not. Ask which change would matter to this lender and how much cash it would take. Draining your down payment or your company's operating cash to clear a debt the lender wasn't going to count leaves you weaker on both sides.
A bill your business pays can still be your personal obligation. Once you know how a lender treats it, you can plan the purchase around a budget that will hold up. Before your next conversation about a home budget, pull your financing agreement, flag the personal guarantee clause, and bring it with you for review.

The equipment loan comes out of the company account on a regular schedule, and it has never once bounced. You signed for it personally when the lender asked for a guarantee, and since then it has felt like the business's problem. Then you start planning a home purchase and a mortgage lender asks about it. Knowing what to check before that question comes up keeps your home budget from shrinking after you've already started looking at listings.
If you've sat at the kitchen table working out what your family could afford in Duncan or elsewhere in the Cowichan Valley, you probably left that loan off the page. The business pays it, so it seemed fair to leave it out. Sometimes the lender will agree. But who pays a business loan and who is legally responsible for it are different questions, and a mortgage lender may need answers to both. Learning that late can mean more paperwork, a smaller approval or a closing date that slips.
Check what you personally owe before you set a home budget
A personal guarantee is a promise to repay the company's debt if the company can't. Borrowing directly on your own credit card or line of credit and spending it on the business is different: that debt is yours from day one. Lenders may treat the two differently. A guarantee gives you a reason to look closer before you shop. It doesn't mean your approval will fall.
Identify what you signed. Pull every business financing agreement, lease and supplier credit application from the last few years and look for a guarantee clause with your name on it. People skip this because incorporating felt like it separated them from the company. Incorporating doesn't cancel a guarantee you already signed, and a loan you took out in your own name is personal debt whatever it paid for.
Check both credit reports and your agreements. Order your reports from Equifax Canada and TransUnion Canada. Some business debts show up there and some guarantees don't. A clean report isn't a complete list of your legal obligations, so tell your mortgage professional about any guarantee you found in the paperwork, even if neither bureau shows it.
Find out what the lender will count before you move any money
Once you know what you owe, the next question is how a lender will weigh it. The answer varies by lender and by the type of obligation.
Document who actually pays. Gather the loan terms, the current balance, the monthly payment, and business bank statements showing the company making those payments. Most people expect the lender to take their word for it. Records give the underwriter facts to assess.
Ask how the proposed lender will treat each obligation. Will it count the monthly payment, note the guarantee as a possible liability, or ask for more evidence? Debt payments generally go into your debt-service ratios alongside your housing costs. They aren't simply subtracted from your income. Your mortgage payment is already tested at the higher of your contract rate plus 2 percentage points or 5.25%, so a counted business payment can use up more room than you'd expect. Ask for an affordability review using that lender's actual treatment before you trust any budget figure.
Review changes before you move money. Paying a loan down or asking the business lender for a formal release of your guarantee might improve your numbers. It might not. Ask which change would matter to this lender and how much cash it would take. Draining your down payment or your company's operating cash to clear a debt the lender wasn't going to count leaves you weaker on both sides.
A bill your business pays can still be your personal obligation. Once you know how a lender treats it, you can plan the purchase around a budget that will hold up. Before your next conversation about a home budget, pull your financing agreement, flag the personal guarantee clause, and bring it with you for review.
Sources
Read Next
Stay or Switch at Renewal: With the Stress Test Gone, Transfer Costs Decide
The Down Payment Is Only the First Cheque: 7 Costs to Budget Before Buying
September's Slower Spending Gain Leaves the Bank of Canada's Next Move Murky
The Advertised Variable Rate Is a Floor, and Most Borrowers Start Above It